Citigroup (NYSE: C) shares fell 5.60% to $124.53 on October 13, 2026, despite reporting third-quarter earnings that exceeded Wall Street expectations. The bank posted earnings per share (EPS) of $2.85 versus an estimated $2.66, while net income jumped 40% year over year to $5.2 billion.
The selloff reflected a different concern: Citigroup's trading and investment banking businesses slowed from the second quarter, and management warned that fourth-quarter Markets revenue could decline approximately 20% sequentially, or more. Investors were looking beyond the earnings beat to question whether Citi could sustain its recent profitability momentum.
Key Takeaways
C stock dropped 5.60% to $124.53 on October 13, even though Q3 EPS of $2.85 beat the approximately $2.66 consensus estimate.
Markets and investment banking revenues both fell 13% quarter over quarter, while company-wide net income declined 10% from Q2.
Management expects Q4 Markets revenue to decline around 20% sequentially, potentially more, although Citi raised its full-year return on tangible common equity outlook to above 11%.
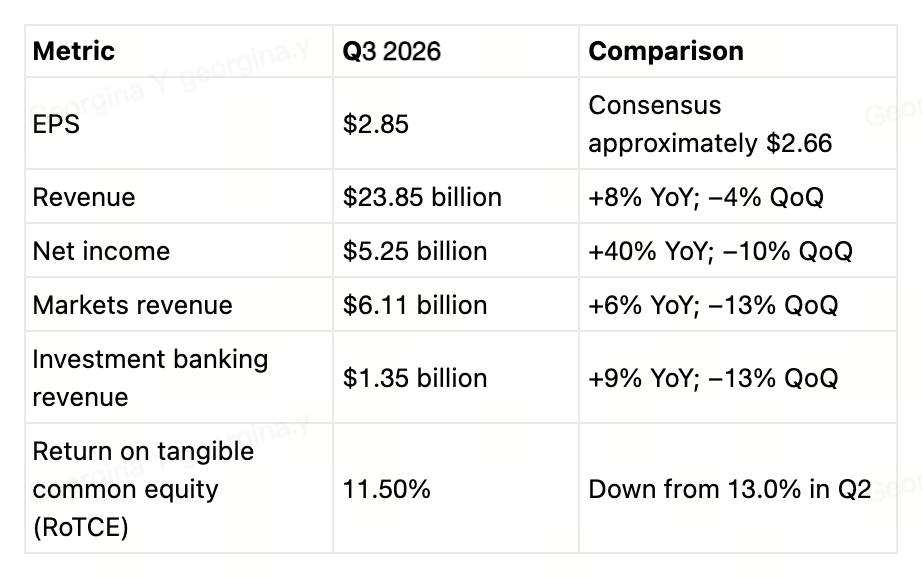
| Metric | Q3 2026 | Comparison |
| EPS | $2.85 | Consensus approximately $2.66 |
| Revenue | $23.85 billion | +8% YoY; −4% QoQ |
| Net income | $5.25 billion | +40% YoY; −10% QoQ |
| Markets revenue | $6.11 billion | +6% YoY; −13% QoQ |
| Investment banking revenue | $1.35 billion | +9% YoY; −13% QoQ |
| Return on tangible common equity (RoTCE) | 11.50% | Down from 13.0% in Q2 |
The headline numbers were strong. However, the 40% reported net income growth partly reflected a $714 million after-tax Banamex-related goodwill impairment in the prior-year quarter. Excluding that item, net income increased approximately 17% year over year.
This distinction matters because investors evaluating recurring profitability may place more weight on underlying earnings growth than on reported growth boosted by an unusually weak comparison period.
Why Did Citigroup Stock Drop After Beating Earnings?
1.Trading and investment banking momentum weakened
Citigroup's Markets division generated $6.11 billion in revenue, down 13% from $7.01 billion in Q2. Equity trading revenue fell 25% sequentially, while fixed-income trading declined 7%.
Investment banking revenue also declined 13% quarter over quarter to $1.35 billion. Equity underwriting fell 19%, and debt underwriting decreased 18% from the previous quarter.
These results still represented year-over-year growth, but they showed that the exceptionally strong activity earlier in 2026 was moderating.
The slowdown was visible in broader profitability. Citi's net income fell 10% sequentially, while RoTCE dropped from 13.0% to 11.5%, according to its
SEC-filed quarterly earnings results.
2.Management warned of a sharper Q4 Markets slowdown
The forward-looking guidance was another important part of the market reaction.
During Citi's
October 13 earnings conference call, CFO Gonzalo Luchetti said fourth-quarter Markets revenue could experience a seasonal decline similar to last year's approximately 20% sequential drop, potentially somewhat larger given the strong performance earlier in 2026.
That outlook suggests another quarter of softer trading revenue, even though management described the pattern as normal seasonality rather than a structural deterioration.
CEO Jane Fraser also emphasized that the expected decline reflected typical fourth-quarter trading patterns.
Still, for investors focused on near-term earnings momentum, the outlook introduced a clear reason for caution.
3.Credit provisions and investment spending remain important
Citigroup's total provision for credit losses rose 6% year over year to $2.59 billion, reflecting portfolio growth and changes in the macroeconomic outlook.
Operating expenses declined 2% on a reported basis, but increased 3% after adjusting for the prior-year impairment. The bank continues to invest in technology, talent and business expansion while working to improve efficiency.
Citigroup's efficiency ratio improved substantially year over year to 58.5%, although it increased from 57.4% in Q2.
These figures highlight the challenge facing the bank: maintaining revenue growth while balancing investment spending, credit costs and profitability improvements.
What Does Citi's Q4 Outlook Mean for C Stock?
Despite the selloff, management did not reduce its overall profitability target. Citi raised its full-year 2026 RoTCE outlook to above 11% and maintained its longer-term objectives.
The bank also returned $4.1 billion to common shareholders during Q3 through share repurchases and dividends, including approximately $3 billion in buybacks.
The next factors investors should monitor are:
Q4 Markets revenue: Whether the seasonal decline stays near management's approximately 20% expectation or proves more severe.
Profitability and expenses: Whether Citi can deliver its full-year RoTCE outlook above 11% and maintain an efficiency ratio below 60%.
Capital returns: Whether continued share repurchases and dividend payments help support shareholder returns while the bank funds further growth.
Is Citigroup Stock a Buy After the 5.6% Drop?
Citigroup's Q3 report was not fundamentally weak. The bank delivered revenue growth, beat earnings expectations and improved profitability versus a year earlier.
However, the October 13 selloff highlighted a gap between strong historical results and expectations for future earnings.
For investors, the central question is whether the slowdown in trading and investment banking reflects ordinary quarterly seasonality or a longer-lasting moderation in profitability.
The company's fourth-quarter results and progress toward its 2027–2028 RoTCE target of 11%–13% will help answer that question.
For now, Citi's earnings beat and 5.6% share-price decline illustrate how markets can prioritize the next quarter's outlook over the most recent quarter's headline performance.