Hong Kong Solana ETF: Can SOL Follow Bitcoin's Path?
Overview
Hong Kong is expanding regulated access to Solana with the listing of the Pando Solana ETF on October 13, 2026. The product, trading under stock code 2831 on the Hong Kong Stock Exchange, becomes the market’s second spot Solana ETF rather than its first. ChinaAMC launched its own Solana ETF on October 27, 2025, giving investors almost a year of real-world data against which the new product can be judged.
That history changes the key question. The launch is no longer simply about whether regulators will permit a Hong Kong Solana ETF. It is about whether a second issuer can deepen liquidity, attract incremental capital and turn regulated SOL exposure into a meaningful institutional allocation channel.
The early benchmark remains modest. ChinaAMC reported net asset value of approximately $4.20 million as of October 12, 2026. That shows why ETF access should not be confused with ETF demand. Bitcoin demonstrated that a regulated wrapper can become a major capital channel when institutional appetite already exists; SOL still needs to prove that comparable demand can develop.
For the market, the most useful signals after listing will therefore be AUM growth, creations and redemptions, turnover, tracking quality and whether competition between issuers expands the investor base rather than merely splitting existing demand.
Key Takeaways
- Pando Solana ETF begins trading in Hong Kong on October 13 under stock code 2831.
- It is Hong Kong’s second Solana ETF, following ChinaAMC’s October 2025 launch.
- ChinaAMC’s Solana ETF had approximately $4.20 million in NAV as of October 12, providing an early demand benchmark.
- ETF listing is market access, not evidence of institutional inflows.
- The real test is whether issuer competition can improve liquidity and build sustained SOL allocations.
What Does the New Hong Kong Solana ETF Actually Change?
The immediate change is operational rather than technological. Investors using a regulated securities account can gain SOL exposure through an exchange-traded product instead of directly opening a crypto exchange account, managing wallet infrastructure or holding private keys.
For some institutions, that distinction matters considerably. Direct cryptocurrency ownership can introduce additional custody, compliance, valuation and operational procedures. An ETF can fit more naturally within portfolio-management systems that already handle listed securities.
That does not mean every institution can or will allocate to the product. Internal mandates, suitability requirements, volatility limits and digital-asset policies can remain restrictive even when an exchange-listed wrapper is available.
The Hong Kong Solana ETF therefore removes one layer of friction without eliminating the investment decision itself.
Does a Hong Kong Solana ETF Mean Institutions Are Buying SOL?
No. A regulated investment vehicle creates a channel for capital; it does not create the capital itself.
This distinction is particularly important because Hong Kong already has a live case study. ChinaAMC Solana ETF began trading on October 27, 2025, yet its disclosed NAV stood at approximately $4.20 million as of October 12, 2026.
That does not make the product unsuccessful. Smaller ETFs can still provide useful regulated access, and market size depends on distribution, investor eligibility, fees and the scale of the local ETF ecosystem. But it demonstrates why the arrival of a second fund should not automatically be translated into assumptions about large SOL purchases.
The useful evidence comes after listing: net creations, AUM, turnover and persistent investor participation.
Can SOL Follow the Bitcoin ETF Institutional Path?
Bitcoin provides the obvious comparison because spot Bitcoin ETFs demonstrated how a familiar securities wrapper can convert previously inaccessible or operationally difficult crypto exposure into institutional portfolio exposure.
But the investment case for SOL is structurally different.
Bitcoin is commonly evaluated as a scarce monetary asset, portfolio diversifier or macro-sensitive store-of-value exposure. Solana is a smart-contract platform whose value proposition is much more closely connected to network usage. Investors assessing SOL may therefore pay greater attention to stablecoin settlement, decentralized exchange activity, application revenue, payments, tokenization and developer activity.
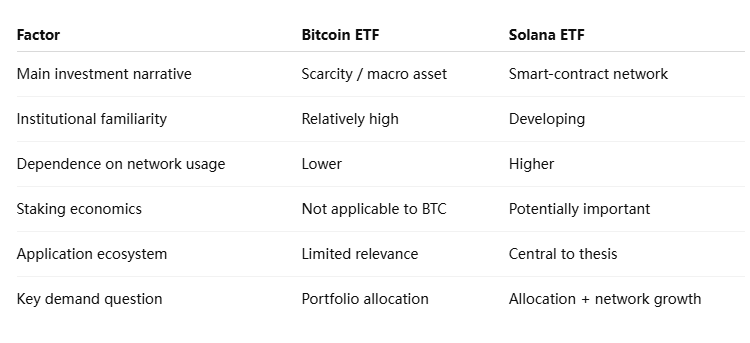
This means the Hong Kong Solana ETF does not simply need SOL prices to rise. For long-term institutional demand, allocators may also need confidence that Solana can sustain meaningful economic activity and maintain its role within crypto infrastructure.
Bitcoin's ETF path is therefore useful as proof that regulated wrappers can unlock demand, but it should not be treated as a template guaranteeing the same capital response for every crypto asset.
Hong Kong Already Had a Solana ETF—Why Does a Second Matter?
A second issuer can still matter even if the first product remains relatively small.
ETF markets develop through competition. Additional issuers can create pressure on management fees, improve market-making coverage and increase distribution through different brokerage and wealth-management channels. More products can also encourage arbitrage activity between ETF shares, NAV and the underlying asset, potentially improving secondary-market efficiency.
The relevant chain is:
issuer competition → broader distribution → stronger market making → tighter spreads → potentially deeper demand
None of these outcomes is automatic, but they provide a more useful framework than treating each new ETF launch as a standalone bullish event.
The existence of a first product also makes Pando's launch more analytically valuable. Investors can compare two issuers operating within the same jurisdiction rather than comparing a Hong Kong SOL ETF with U.S. Bitcoin funds whose market scale, investor base and regulatory history are substantially different.
The next several months should show whether Pando attracts genuinely new assets or mainly competes for the same pool of investors already able to access SOL through ChinaAMC.
Why Hong Kong Matters for Asia's Crypto ETF Market
Hong Kong's importance extends beyond the absolute size of an individual fund. It provides a regulated laboratory for testing whether assets outside Bitcoin and Ethereum can support conventional ETF infrastructure.
If Solana products establish consistent AUM, liquid secondary markets and reliable creation-redemption activity, the data can help issuers evaluate whether other large crypto assets justify similar products. Conversely, weak demand would demonstrate that regulatory permission alone does not guarantee a commercially viable altcoin ETF market.
This distinction matters for the broader Asian digital-asset industry. A successful ETF framework can connect crypto markets with brokers, asset managers and wealth-management platforms that may be reluctant to interact directly with blockchain wallets.
But the demonstration effect should not be overstated. Hong Kong regulation does not automatically determine how Singapore, Japan, South Korea or other markets will treat equivalent products. Each jurisdiction has its own securities rules and investor-protection standards.
What Hong Kong can provide is evidence—not a regulatory blueprint.
What Should Investors Watch After Pando Starts Trading?
The launch date itself is less informative than what happens afterward. The strongest indicators are relatively straightforward:
- AUM growth: shows whether capital is actually entering the product rather than simply changing hands on the exchange.
- Net creations and redemptions: distinguish primary-market demand from secondary trading.
- Daily turnover: indicates whether an active market is developing around the ETF.
- Premium or discount to NAV: helps measure market-making efficiency.
- Bid-ask spreads: narrower spreads generally suggest deeper executable liquidity.
- Performance relative to ChinaAMC's ETF: shows whether the second issuer is expanding the market or simply redistributing existing demand.
SOL spot-market behavior matters as well. If the funds grow meaningfully, creation and redemption processes can create a tighter link between ETF demand and underlying SOL liquidity. At small AUM levels, however, the impact on the global SOL market is likely to remain limited.
That is why headlines about “institutional access” should always be separated from measurable institutional allocation.
Could a Solana ETF Directly Boost SOL Liquidity?
Potentially, but the effect depends on scale.
An ETF creates another venue through which investors can express demand for SOL exposure. If net creations become large, authorized participants and market makers may need to obtain or hedge SOL exposure, creating additional interaction between the securities market and the underlying crypto market.
At modest AUM, this mechanism remains small relative to global SOL trading activity. The ETF may still improve local market access without becoming a major source of price discovery.
There is also an important distinction between ETF liquidity and underlying asset liquidity. A product can show healthy turnover because market makers efficiently trade its shares even when underlying fund assets remain relatively small.
For this reason, turnover alone should not be used as evidence of major capital inflows.
MEXC View: ETF Approval Is Only the Start of Price Discovery
The key question for SOL is no longer whether a regulated Solana ETF can exist in Hong Kong. The market has already answered that. The more important issue is whether regulated access can generate persistent allocations large enough to influence liquidity and institutional portfolio behavior.
Pando's entry creates a better test because Hong Kong now has issuer competition rather than a single product. If combined AUM expands substantially instead of merely moving between funds, that would provide stronger evidence that the investable market itself is growing.
For the broader crypto ETF sector, this distinction is important. Regulatory approval establishes infrastructure. Capital flows establish product-market fit.
The indicators worth watching are therefore net creations, total category AUM, spreads and the percentage of activity represented by genuinely new capital. Those data will say more about institutional SOL adoption than the number of ETFs listed.
Risks and Limitations
Several constraints make comparisons with Bitcoin ETFs especially difficult.
- Market-scale risk: Hong Kong's ETF ecosystem is different in size and distribution from the U.S. market.
- Demand risk: regulated access does not ensure that institutional investors have allocation mandates for SOL.
- SOL volatility: higher volatility can limit position sizes for conservative portfolios.
- Tracking risk: fund returns can diverge from underlying SOL because of fees and operating mechanics.
- Liquidity concentration: strong exchange turnover does not necessarily imply large fund inflows.
- Regulatory risk: virtual-asset investment rules may continue to evolve.
- Network risk: Solana ETF demand is ultimately exposed to the economic and technical health of the underlying network.
Staking is another structural consideration. SOL naturally offers staking economics at the protocol level. Depending on how an ETF handles or does not handle those rewards, investors may compare the convenience of the fund with the opportunity cost of holding SOL directly.
That makes product structure more important for SOL than for Bitcoin.
Hong Kong's Second Solana ETF Is a Demand Test
The launch of Pando's Hong Kong Solana ETF expands the regulated infrastructure available to investors who want SOL exposure, but it should not be interpreted as proof that a Bitcoin-style institutional capital wave has begun.
Hong Kong already has an important benchmark. ChinaAMC's Solana ETF has operated since October 2025 and reported approximately $4.20 million in NAV on October 12, 2026. The number demonstrates both sides of the story: regulated SOL products can operate successfully within the securities market, but regulatory availability alone has not yet produced Bitcoin-scale asset accumulation.
The second product makes the market more interesting because it introduces issuer competition. Fees, distribution, market making and investor awareness can all improve when more than one provider is competing for assets.
The next stage of the story therefore begins after October 13. If combined Solana ETF assets rise steadily, net creations persist and liquidity improves without simply shifting assets between products, Hong Kong will have stronger evidence that SOL is developing a genuine institutional allocation channel.
If demand remains limited, the conclusion will be equally useful: altcoin ETF approval and institutional adoption are two separate milestones. For the Hong Kong Solana ETF market, the listing opens the door; actual flows will determine whether institutions walk through it.
Sources
Hong Kong Exchanges and Clearing — Pando Solana ETF listing and trading arrangements:
https://www.hkex.com.hk/
Hong Kong Exchanges and Clearing — Pando Solana ETF stock admission:
https://www.hkex.com.hk/Services/Circulars-and-Notices/Participant-and-Members-Circulars
Risk Disclaimer: This article is for reference only and does not constitute investment advice. The cryptocurrency market is highly volatile. Please make decisions cautiously based on your individual circumstances.
Ayrıca Şunları da Beğenebilirsiniz
Why Is ZEC Rising? Zcash Rebounds as Quantum-Security Narrative Gains Attention
Why Are Memory Chip Stocks Falling Despite Strong AI Demand?